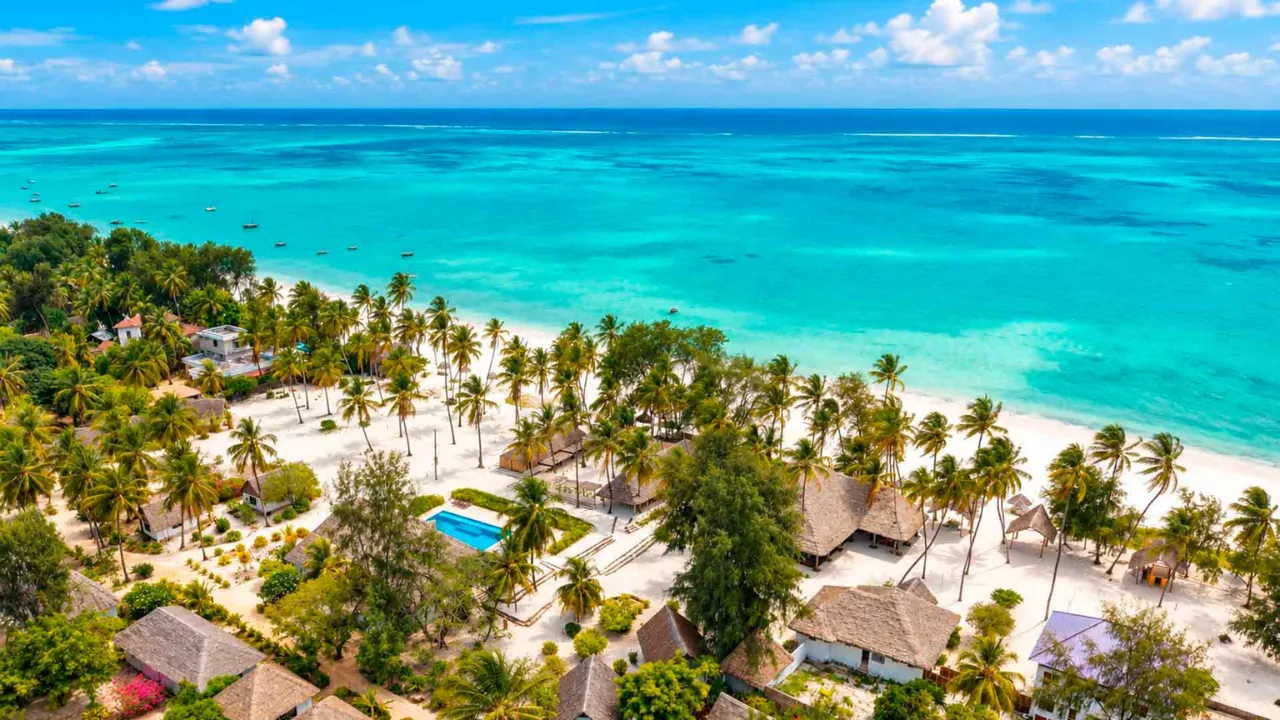
For a decade, the European city apartment rented by the night was one of the continent's favourite small investments, and that era is now ending on a schedule you can look up. The short-term rental regulations arriving in Europe in 2026 do not ban anything themselves, which is precisely what makes them effective: they make every existing local restriction enforceable at scale, and they arrive as cities from Amsterdam to Barcelona tighten the restrictions being enforced. The investors affected are asking a reasonable question: if the yield is being regulated out of the European calendar, where does it go? In this guide, we'll explore what actually changed in Europe, what the rules do to a yield model, the investor migration already underway, Zanzibar's regulatory position stated plainly and without gloating, the net comparison between a capped city flat and a Paje apartment, the honest risks of regulation-light markets, and who should make this move and who should not.
What changed in Europe, the 2026 short-term rental rules
The change is administrative in form and structural in effect, and it has two layers that work together.
The EU data sharing framework
Regulation (EU) 2024/1028, applying from 20 May 2026, builds the machinery: a standardised registration system in which hosts obtain a unique registration number displayed on every listing, and interoperable data sharing under which booking platforms report activity to authorities. The regulation deliberately does not set night caps or decide where short-term rentals are legal; it leaves those choices local. What it removes is the enforcement gap. A city rule that once relied on complaints and manual checks can now be audited by matching platform booking data against the registration record, listing by listing, month by month. In plain terms, Europe did not write new restrictions in Brussels. It made the existing ones real.
Day caps and registration by city
The restrictions being made real are already substantial and still tightening. Amsterdam has long capped primary-residence letting at 30 nights per year, with proposals reported to cut some zones to 15 nights. Paris and Lyon enforce principal-residence limits through municipal registration that platform data now makes matchable. Barcelona has moved to phase out tourist apartment licences altogether. The pattern across the continent is consistent in direction: fewer legal nights, tighter licensing, higher compliance costs, and a political climate in which the short-term rental investor is the pressure valve for a housing debate much larger than tourism.
The enforcement mechanics deserve a paragraph of their own, because they are what separates 2026 from every previous round of rules. Under the new framework, the registration number is a listing requirement: platforms must display it, conduct checks on the information hosts provide, and share booking activity with authorities through the interoperable data systems. An unregistered listing is not a quiet risk anymore; it is visible to the platform obliged to act on it and to the authority receiving the data feed. For a decade, the gap between rules and enforcement was where marginal European STR yields actually lived. The regulation's whole design is to close that gap, and an investor should assume it succeeds.
What the rules do to a yield model
A rental yield is nights sold multiplied by rate, minus costs, divided by price, and the regulation attacks the first term directly.
A worked example with a capped calendar
Run the arithmetic structurally, without needing any city's exact rates. A professionally run holiday unit in a strong market sells somewhere between 180 and 310 nights a year, and the published Zanzibar operating scenarios, 50, 65, and 85 percent occupancy, translate to 183, 237, and 310 nights. Now cap the same asset at 30 legal nights. The calendar has lost between 84 and 90 percent of its sellable inventory, and no nightly rate a city will bear can multiply its way back across that gap. The capped flat's rental economics collapse toward those of a hobby: a few premium weeks, then a legally mandated silence, with the fixed costs, service charges, taxes, insurance, running all twelve months regardless.
The second-order costs stack on top of the calendar loss. Registration and compliance are administrative overhead that small operators bear disproportionately. Tourist taxes and reporting obligations continue on the nights that remain. And the two exits available to the owner both reprice the asset: converting to a long-term tenancy means regulated city rents and tenant protections designed for a different business, while selling means finding a buyer who has run the same capped arithmetic you just did, in a market where every comparable owner faces the same choice at the same time. A cap does not reduce a yield. It changes the asset class, and the price eventually follows the asset class.
The investor migration already underway
Capital responds to arithmetic, and the response is visible in the reporting: as European city rules tightened through 2024 and 2025, short-term rental investment interest shifted toward markets where the calendar is not the constrained resource, southern destinations inside Europe, and increasingly, destinations beyond it. Zanzibar's own demand data records the arrival end of that shift: foreign capital reaching the island from Europe, the Gulf, and increasingly the United States, non-resident buyers near one third of transactions, and the market context set out in the Zanzibar property market outlook for the year ahead.
The destination side of the ledger explains why the flow found this island in particular. Zanzibar closed 2025 with 917,167 international arrivals, up nearly 25 percent year on year, formally crossed the one million annual visitor milestone, and opened 2026 with January arrivals up a further 19.2 percent. European holidaymakers, the same guests the capped city flats were serving, make up 66 percent of the island's visitor mix, staying around 8 nights per trip. In other words, the investor migrating from a European STR is not changing customers. They are following the same guest to a calendar the law still allows them to sell.
The honest framing of this migration matters, and it is not triumphant. European cities are not wrong to regulate; they are answering housing pressures their voters live with, and an investor reading this article may well agree with the policy while declining to donate their yield to it. The question is not whether Europe's rules are good. It is where an income asset still works as designed, and that is a question about calendars, not politics.
Zanzibar's regulatory position stated plainly
The temptation in an article like this is to sell Zanzibar as the unregulated opposite, and it would be both wrong and a disservice. The position is more specific.
What is regulated
The investment layer is firmly regulated, and recently more so. Real estate projects must be registered with and approved by the Zanzibar Investment Promotion Authority (ZIPA) before marketing or sales, purchase agreements are valid only once ZIPA has endorsed them, and developers operate under an annually renewed licence. Inside a condo-hotel, the rental activity itself is governed too, contractually rather than municipally: in the standard structure, short-term letting runs exclusively through the development's management program, and an owner cannot independently list on Airbnb or Booking.com, with personal use and long-term tenancies of six months or more as the alternatives. There are rules here. They are simply aimed at protecting the investment rather than capping its calendar.
What is not
What Zanzibar does not have is the European apparatus this article opened with: no night caps on tourist accommodation, no municipal licence lotteries for individual hosts, no phase-out schedules. The island's policy posture runs the other way, because its economics do: tourism is the engine, the government's targets are for more visitors rather than fewer, and the one million annual arrivals milestone was met with expansion plans, not alarm. A destination whose housing pressure is a construction pipeline rather than a residential shortage regulates accommodation differently from a city where every tourist bed was once someone's flat.
Why light regulation cuts both ways
Now the caution, stated as plainly as the advantage. Rules can arrive anywhere, and an investor who moves capital to escape regulation should assume regulation can follow. What the evidence supports is a judgement about direction rather than a guarantee: Zanzibar's recent regulatory activity, the 2023 Investment Act, the 2025 regulations, mandatory ZIPA registration of projects, has consistently formalised and protected the investment channel rather than restricted it, and the island's fiscal interest in tourism argues for that direction persisting. But "argues for" is not "ensures," and the honest position is that regulatory risk exists here as everywhere, currently pointed in the investor's favour, and worth monitoring rather than assuming away.
Comparing net positions, a capped city flat versus a Paje apartment
Put the two assets side by side as calendars first. The capped European flat sells 30 nights where its market could fill 200, and its yield is whatever those 30 premium nights net after full-year fixed costs. The Paje apartment sells against the island's operating scenarios, 183 to 310 nights, in a market whose professionally managed beach stock delivers 12 to 15 percent gross, with the published condo-hotel model netting 13.3 to 22.9 percent across its occupancy cases after management, service fees, and withholding tax. The full architecture behind those numbers, including what they assume, sits in what rental yield can you really expect from a Paje apartment.
The comparison should be completed honestly with the columns Europe wins: the city flat sits in a mature legal system, a deep resale market, and a currency and jurisdiction the owner already knows, advantages of the same kind, if not the same degree, as the Mauritius comparison worked through in Zanzibar vs Mauritius for the European second home buyer. What has changed is that the city flat's income column no longer competes, by law rather than by market, and an asset whose defining advantage was yield does not survive the removal of its yield with its logic intact.
One further column belongs in the comparison for a euro-based investor: currency. The capped flat earns euros against euro costs, which is simple and undiversified. The Paje apartment is priced and earns in US dollars, which adds a currency dimension to both the risk and the diversification of the position, and which deserves conscious planning rather than discovery, particularly around the staged payments of an off-plan purchase. The mechanics, and the habits that keep dollar income moving cleanly to a European account, are covered in the financing and repatriation guides in this library.
The honest risks of regulation-light markets
Every risk this library has catalogued applies to the investor arriving from a capped market, and arriving frustrated is no reason to skip them. Emerging market texture is real: younger institutions, a shorter track record, thinner liquidity than a European city, and the execution risks of off-plan buying, all of which have their own disciplines and their own articles. Demand concentration is real: the island's income depends on tourism continuing to grow, and the downside case deserves the full treatment given in what a bad year looks like, stress testing a Paje rental at low occupancy. And regulatory evolution is real, as the section above says without flinching.
The point of naming the risks is proportion, not deterrence. The European investor's alternative is not risk-free; it is a different risk book, political and regulatory rather than developmental, and 2026 is the year that book's costs came due. The rational move is not to flee one risk profile blindly into another. It is to price both, at the downside case, and let the arithmetic choose.
Who should make this move and who should not
The move fits a specific investor. They own or were about to buy European short-term rental exposure, and the new rules have repriced it. They want yield as the primary objective, not a familiar jurisdiction as comfort. They can commit for years, absorb emerging-market texture, and run their decision on the stress-tested numbers rather than the brochure. For that investor, redirecting capital from a 30-night calendar to a 237-night one is not exotic. It is the same yield discipline that built their original position, applied to a map that changed.
The move does not fit the investor whose real attachment is to the European asset itself, the flat they can visit, in the city they know, under laws they grew up with. Nor does it fit anyone who cannot tolerate the risks named above, or who is moving purely on frustration rather than analysis. The honest test is the same one this library applies everywhere: if the downside number works for you, the upside takes care of itself, pole pole. If a rule change at home started this search, run your capped numbers against the calculator here and compare the two honestly.

